Hi, friends.
Having condo insurance—also known as HO6 insurance—is part and parcel of buying a condominium. But, as integral as insurance is to the condo-buying process, some myths and misconceptions still surround it. Here, Staci McCann, our senior portfolio manager, debunks a couple of common untruths.
Fact or Fiction: I don’t have a mortgage, so I don’t need condo insurance.
This one’s fiction, says Staci. “Anyone with a mortgage is required by their mortgage company to obtain HO6 insurance. What we’ve encountered many times, however, is unit owners who don’t have a mortgage and think that, as a result, they don’t need homeowners insurance. But that’s not the case.”
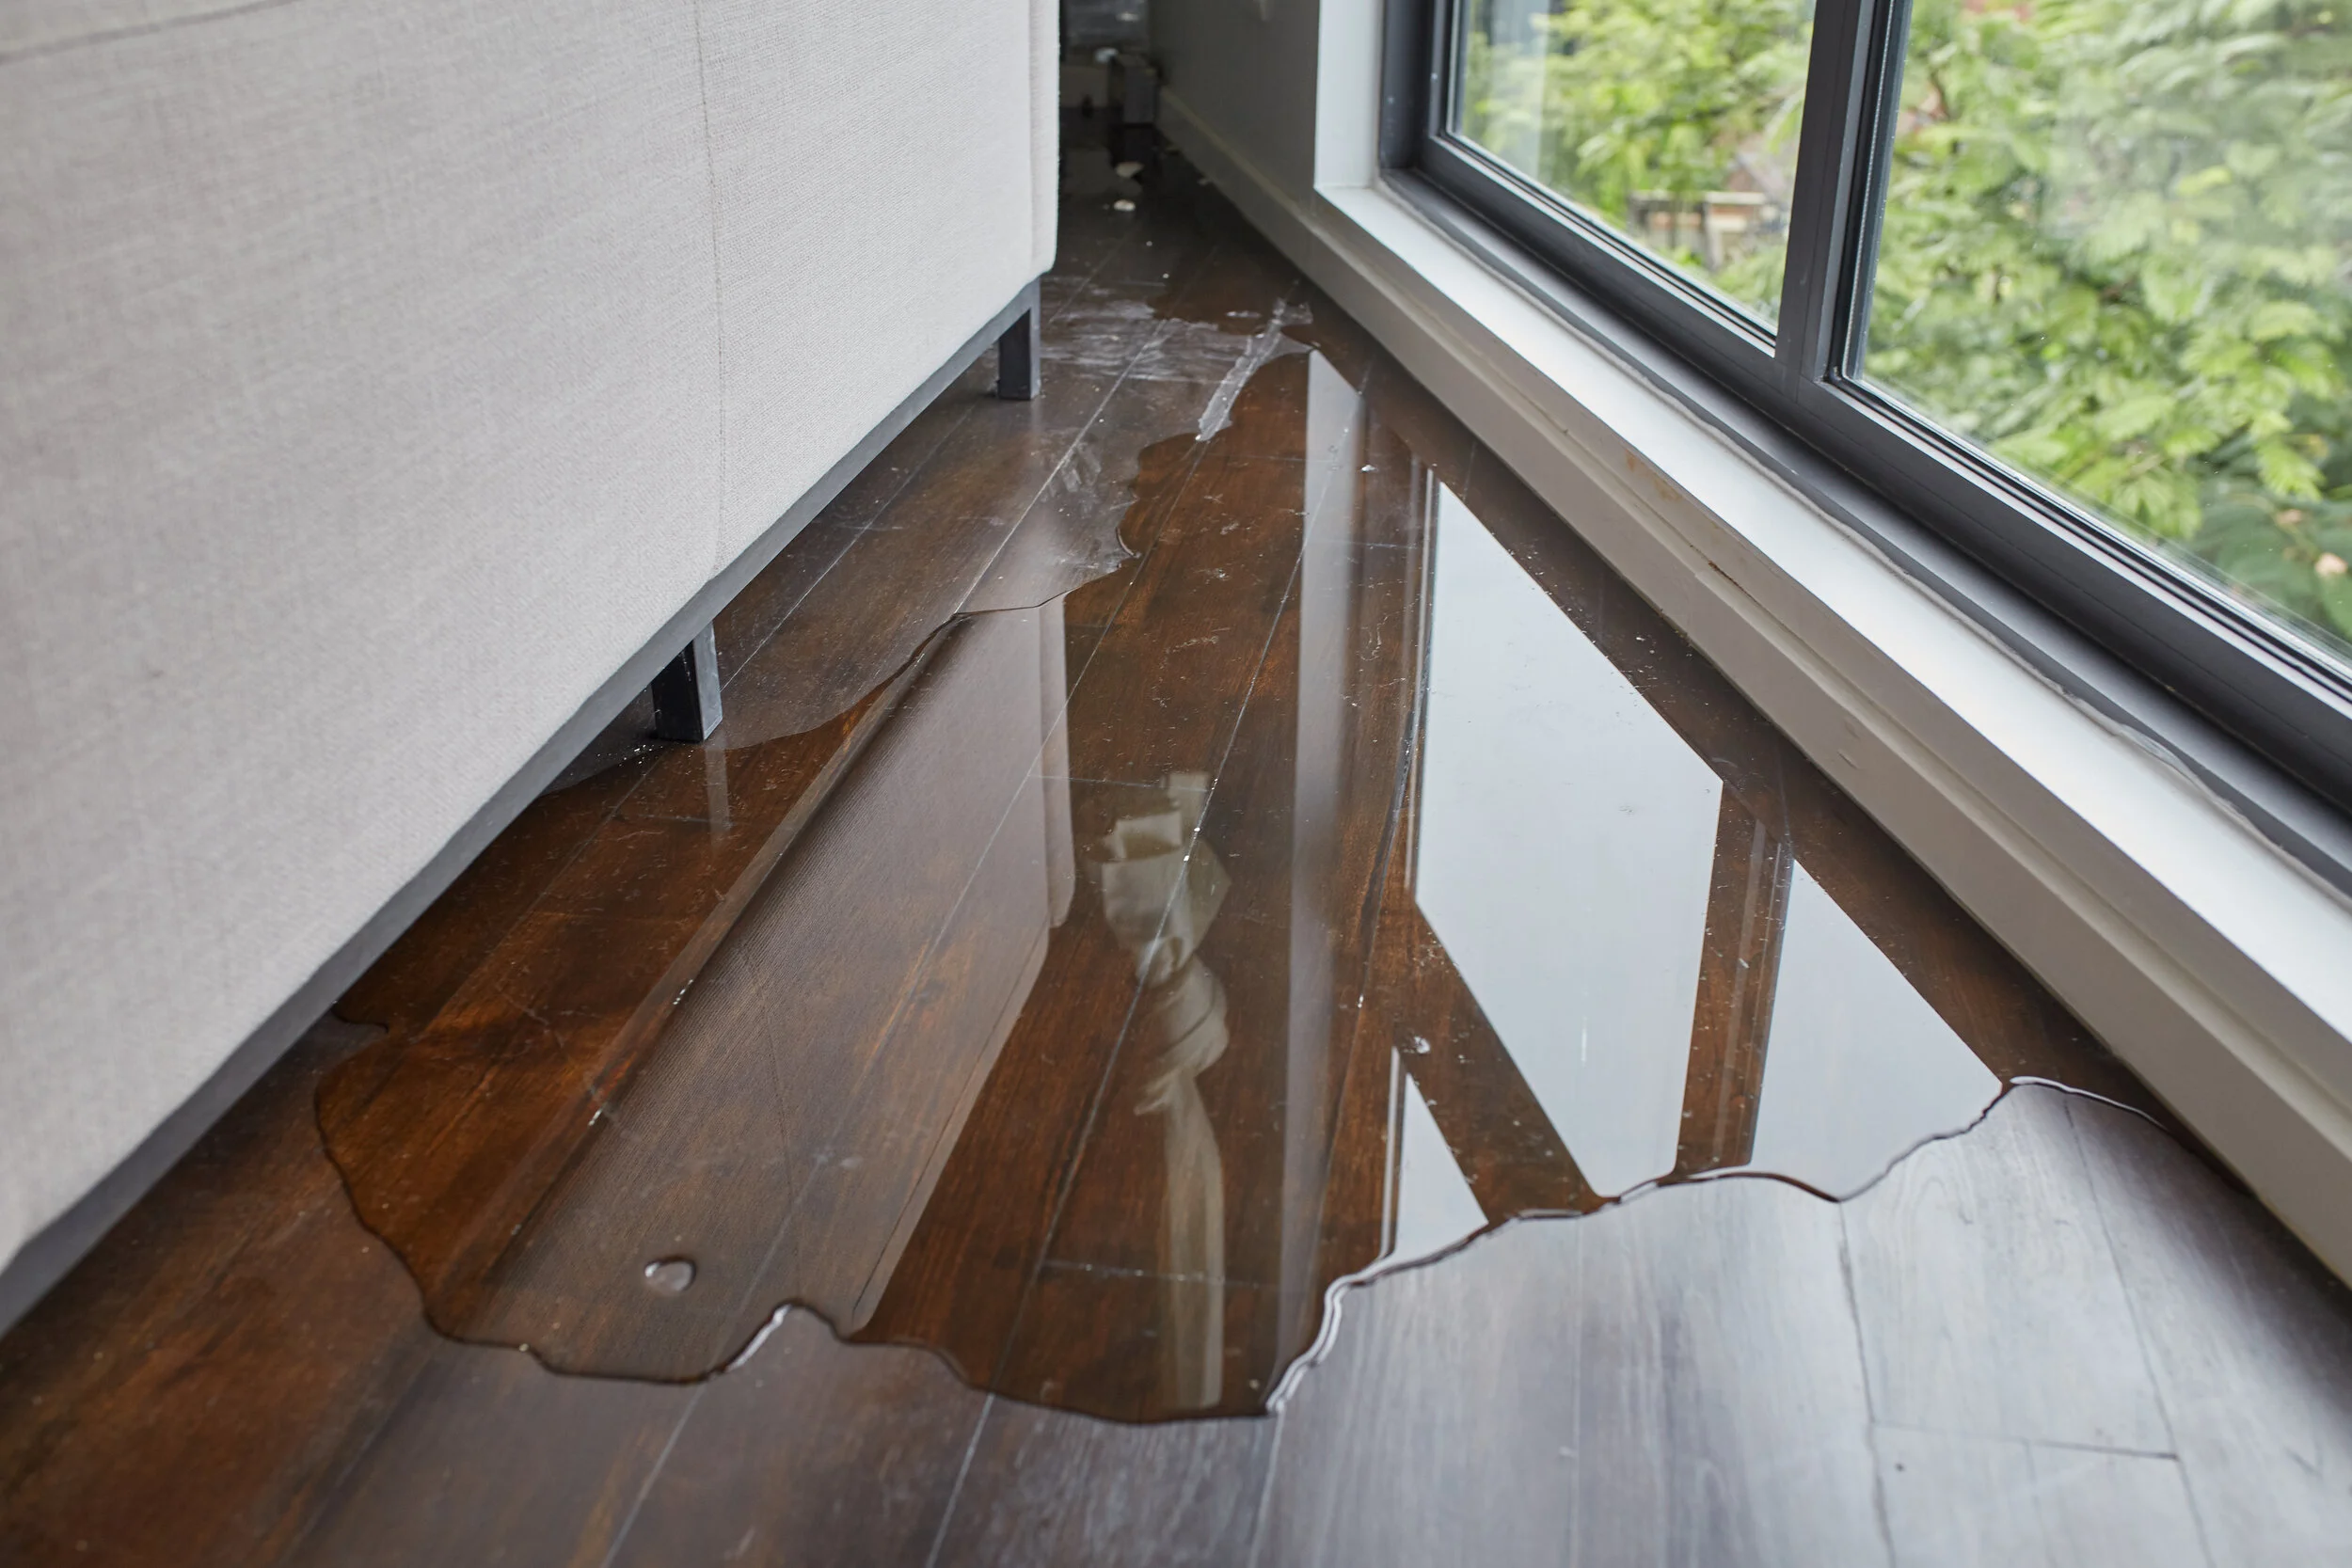
“In the event of a loss in your unit due to a fire, flood, or other disaster, the master policy is first subject to its deductible,” Staci says. What that means: “If the deductible is $25,000, then the unit’s owner is responsible for paying the first $25,000 of the loss before the master policy kicks in. So, if you don’t have insurance to cover the deductible, that $25,000 comes directly out of your pocket.” Ouch.
Fact or fiction: The apartment or condo building’s master policy covers everything inside the building and unit.
This one’s fiction, too. “Your Association carries a master insurance policy that covers loss or damages to your condo building and its common areas,” Staci says. “But the master policy only covers the structure itself—the building, the walls, the flooring. It doesn’t cover any of your personal belongings, like furniture, clothing, electronics, some appliances, or jewelry.”
So, if there’s a fire in a unit and everything’s damaged by flames, smoke, or water? “The master policy wouldn’t cover the cleaning or replacement of any of those items,” Staci says. “If you don’t have insurance, all of those items would have to be replaced at your own out-of-pocket expense. This is why we very highly recommend that all unit owners, whether they have a mortgage or not, obtain HO6 insurance.” That’s some sound advice.
Have questions? Drop us a line.
Until next time,
The BRIGS team